Meet the minds

The researchers who turned buyback anomalies into a living map of market behavior

We started with a question no one else was asking — and built a platform to share what we found.

Most platforms tell you what happened. We show you how buyback program characteristics cluster across companies, why those patterns form, and what they reveal about the choices firms make. Our work sits at the intersection of academic rigor and practitioner curiosity — built for analysts who want context, not just numbers.

Get in touch See our approach

Academic foundations

Rooted in peer-reviewed research on repurchase effects and cross-sectional variation.

Practical application

Designed for working analysts who need signal, not noise.

Collaborative inquiry

We learn alongside our community, refining models as markets evolve.

Our story began in a university library and ended up on trading desks. Here is how we got from one to the other.
  • 2018

    The spark

    A late-night observation: firms with similar buyback announcement styles showed oddly divergent post-event returns. We wrote it down.
  • 2019

    The paper

    Months of data cleaning and model testing produced a working paper on cross-sectional repurchase effects. We shared it quietly.
  • 2020

    The conversation

    Analysts started emailing. They wanted the methodology, not just the conclusions. We realized the gap was wider than we thought.

  • 2021

    The prototype

    We built a small tool to visualize buyback characteristic clusters. It was ugly, but it answered the right questions.

  • 2023

    The launch

    Flumveliodlau went live with a full dataset, updated models, and a community of early users who helped us refine everything.
  • 2026

    The next chapter

    We are expanding coverage, adding sector-level lenses, and inviting more researchers to contribute their findings.
Our team

The people behind the platform

Researchers, builders, and market observers who believe context matters.

Our team blends academic training with hands-on experience in equity research and quantitative analysis. We do not claim to predict the future — we build tools that help you understand what the past is trying to say.

Each member contributes to model design, data integrity, or community engagement. We review every dataset update together.
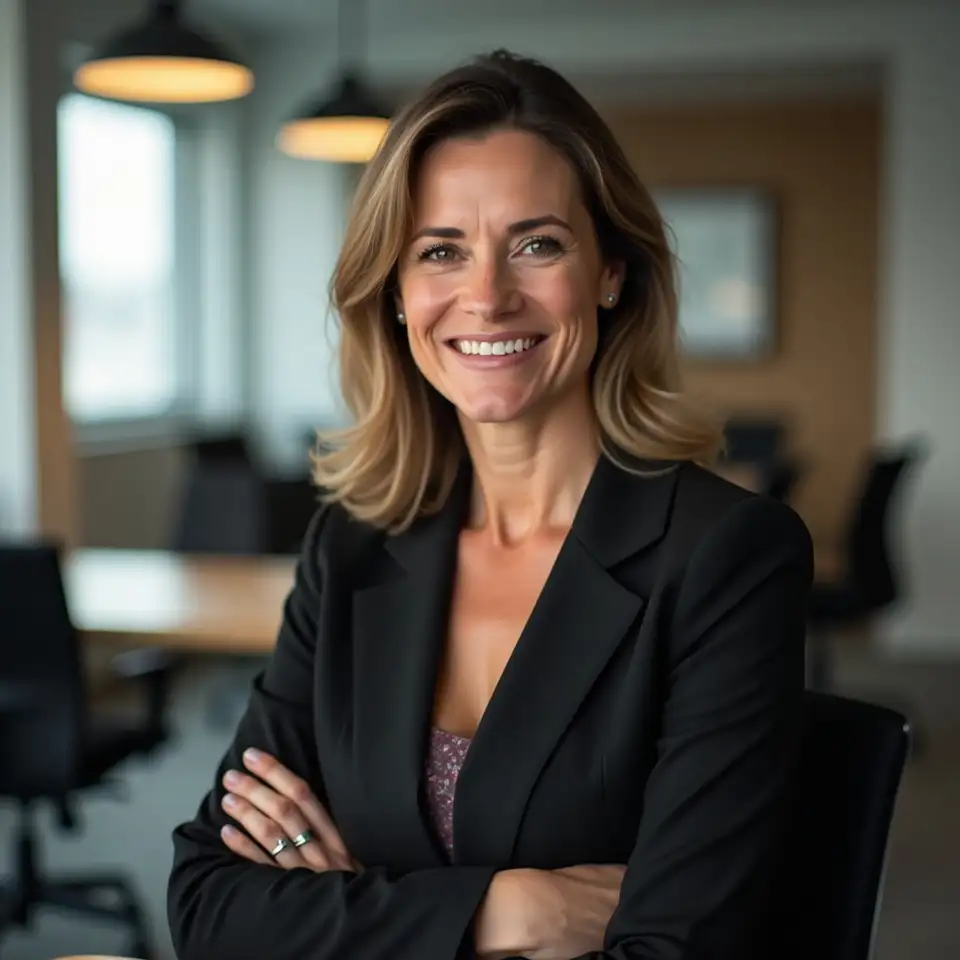
Dr. Elena Voss

Dr. Elena Voss

Lead Researcher

Elena oversees model development and dataset methodology. She previously studied corporate payout policy at a research institute in Dublin.

Elena holds a doctorate in finance and has spent over a decade examining how firms communicate capital allocation decisions to the market.

"The best models are the ones you can explain to a skeptical colleague."
Econometrics Corporate finance Data architecture
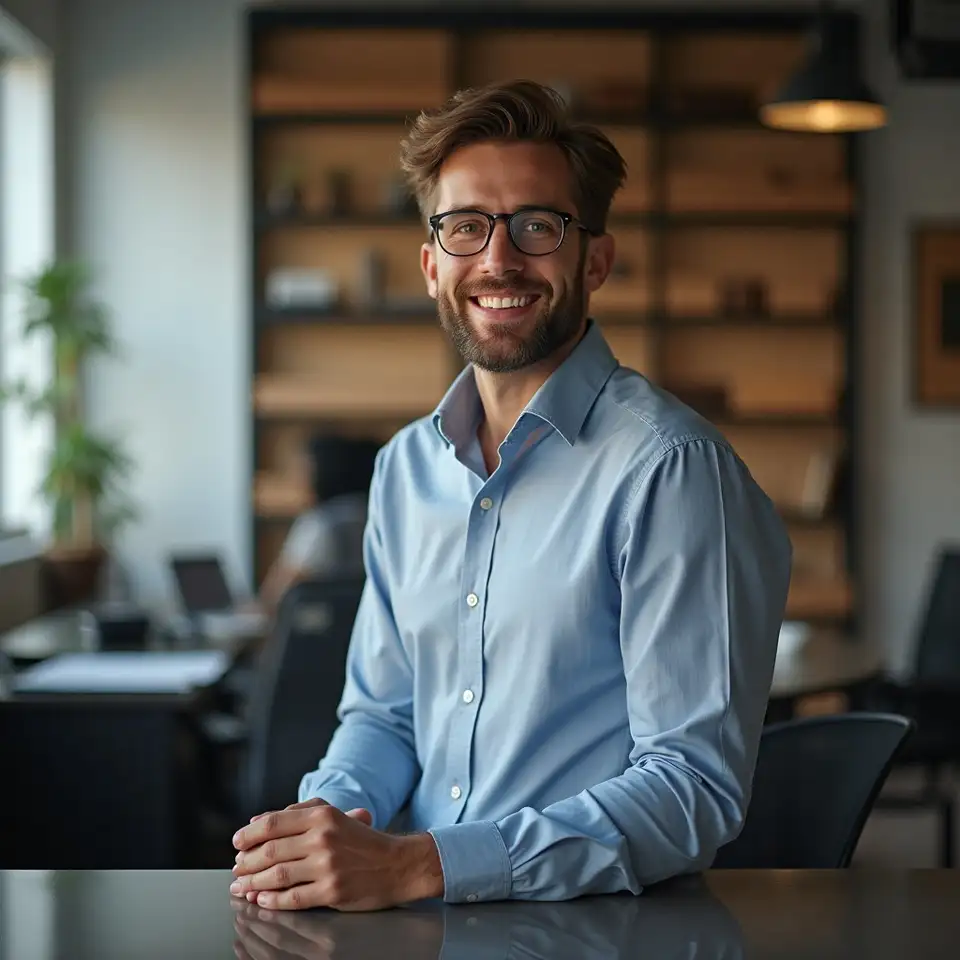
Marcus O'Brien

Marcus O'Brien

Quantitative Analyst

Marcus transforms raw market data into structured signals. He builds the pipelines that keep our models current and reproducible.

Marcus trained in computational statistics and previously worked on risk modeling for a Dublin-based asset research group.

"Clean data is a love language."
Python Signal processing Cloud infrastructure
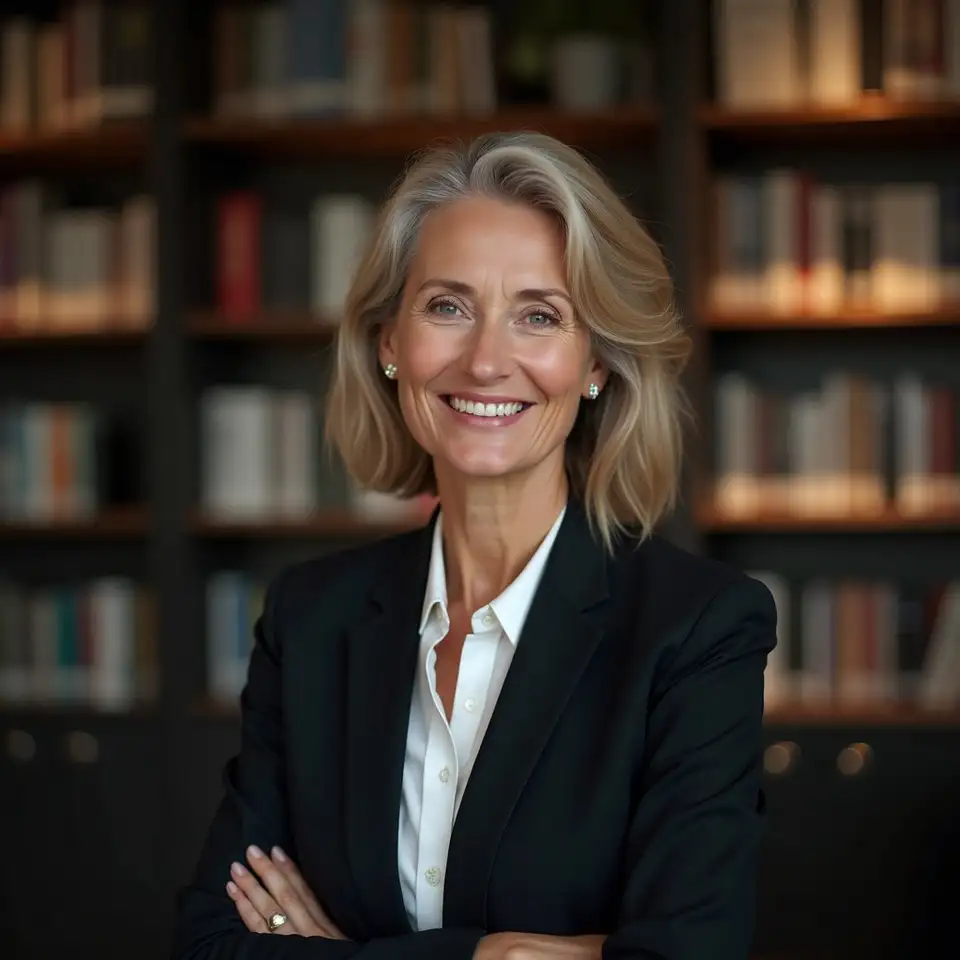
Dr. Aisha Patel

Dr. Aisha Patel

Academic Advisor

Aisha connects our work to the broader research community. She reviews publications and helps us maintain methodological transparency.

Aisha is a professor of finance with a focus on market microstructure and informed trading around corporate events.

"Good research invites disagreement. Great research survives it."

Peer review Market microstructure Research ethics

Interested in contributing research or joining the team? We read every message.

What we stand for

These principles guide every dataset update, model revision, and conversation with our community.

Intellectual honesty

We report findings even when they contradict our hypotheses. A null result is still a result, and we treat it with the same care as a significant one. Our users deserve the full picture, not a curated highlight reel.

Methodological transparency

Every model we publish includes its assumptions, limitations, and the exact data filters applied. We believe you cannot interpret a signal without knowing how it was constructed.

Continuous learning

Markets evolve, and so do our models. We revisit past conclusions regularly, updating them when new evidence demands it. Stagnation is the enemy of insight.

Practical relevance

Academic rigor means nothing if it sits behind a paywall no practitioner can reach. We design our tools for working analysts, not just journal reviewers.

Community respect

Our users are not an audience — they are collaborators. We credit contributions, respond to challenges, and treat skepticism as a feature, not a bug.

Empowerment through clarity

Complexity is not a credential. We work to make sophisticated analysis accessible without dumbing it down. The goal is understanding, not impressing.

Recognition and citations

Our research has been referenced in academic circles and industry forums alike.

Best Working Paper

Recognized for methodological innovation in analyzing cross-sectional buyback announcement effects at a European finance symposium.

2021

Data Transparency Award

Honored for open documentation of model assumptions and replication materials in quantitative finance research.

2022

Industry Collaboration Prize

Acknowledged for bridging academic research and practitioner tools in equity market analysis.

2023

Open Science Citation

Cited in a peer-reviewed journal for contributions to reproducible research practices in corporate finance.

2024

Key moments in building Flumveliodlau.

1 / 3